

When the bank says no, the question becomes “what’s next?”
If you own a home in Edmonton, St. Albert, Sherwood Park, Spruce Grove, Leduc, Beaumont or Fort Saskatchewan and the bank has just said “no,” you’re not alone in looking for a plan B. After the late-October rate increase, more borrowers are finding qualifying tight. A private mortgage is one option that can come up, and it can help. But it’s a tool for getting from one place to another, not somewhere to settle in.
Think of it like crossing the North Saskatchewan: the bridge gets you over the river, but nobody plans to live on the High Level Bridge. The most useful thing you can do before you sign is know exactly where you’re headed on the other side.
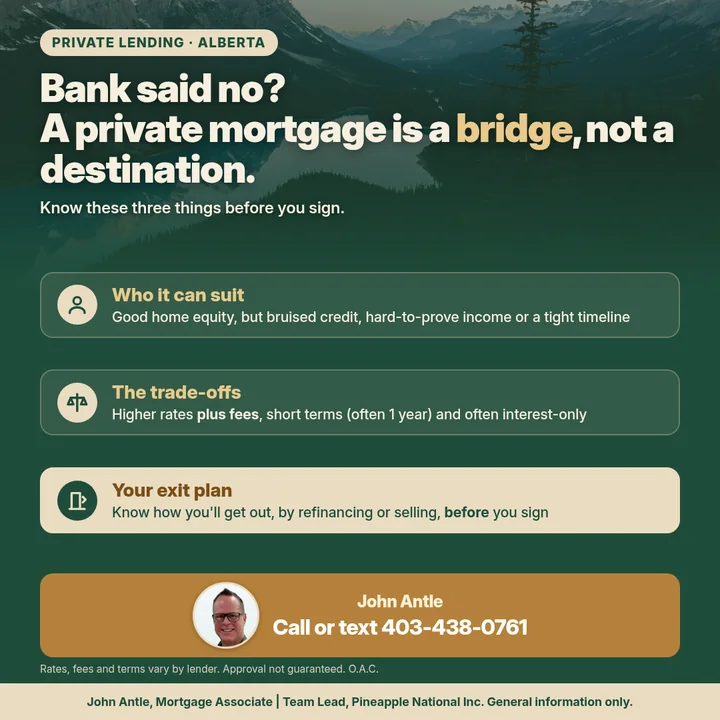
Who a private mortgage can suit
Private lenders look mainly at the property and how much equity you have in it, rather than relying only on the usual bank checklist. That’s why a private mortgage can suit homeowners who have good home equity but, for now, don’t fit a regular lender’s rules because of:
Bruised credit
Missed payments or past credit trouble that a bank won’t look past yet, even though the home itself has solid equity.
Hard-to-prove income
Business owners, contractors and commission earners whose paperwork doesn’t yet show what a regular lender wants to see. See also my self-employed mortgage guide.
A tight timeline
A closing date, a deadline or a payout that can’t wait for a longer approval process.
A clear way back
The best fit is someone who can already describe how they’ll get back to a regular lender, or sell, when the term ends.
The trade-offs, in plain language
- It costs more. Private mortgages come with higher rates plus lender and broker fees. Private lenders themselves have been urging brokers to look beyond the rate: the fees, the renewal terms and the exit strategy all shape what a private mortgage really costs.
- The terms are short. Terms are often one year; industry reports describe terms of 12 to 24 months. That’s a short runway, so the plan has to start on day one.
- Payments are often interest-only. That can keep payments manageable, but you aren’t paying down the balance, so the full amount still has to be refinanced or repaid at the end.
- Every lender is different. Rates, fees and terms vary by lender. Any fees on your file are disclosed in writing in advance, and approval is never guaranteed.
No rate quotes here, on purpose. Private lending is priced file by file. The honest answer to “what will it cost?” comes from looking at your property, your equity and your exit plan together.
Planning your exit: the most important part
The single most important thing about a private mortgage is how you get out of it. Industry panels in September 2026 said exits are taking longer, which makes planning ahead even more important. Before you sign, you should be able to answer these:
Where am I going?
Usually it’s a refinance back to a regular lender. Sometimes the plan is to sell. Either is fine, as long as it’s a real plan.
What has to change for a regular lender to say yes?
Rebuilding credit, filing tax returns that show your income, or finishing whatever made the timeline tight. Name it, and know how long it realistically takes.
Does the timing fit the term?
If the term is a year, the plan has to work in about a year. If it might take longer, ask up front what renewing with the private lender would involve.
Does the plan depend on prices going up?
A realistic exit shouldn’t rely on your home being worth more next year. If the numbers only work with a price increase, that’s a warning sign.
What’s plan B?
If the refinance isn’t ready in time, what happens? Knowing your fallback, including a sale, protects your equity.
Sometimes that conversation shows a private mortgage isn’t the right move at all, and another option, like an alternative lender or a different refinance approach, makes more sense. That’s a good outcome too. You can see everything I help with on the mortgage services page.
Fully online, anywhere in the Edmonton area
Whether you’re in Edmonton, St. Albert, Sherwood Park, Spruce Grove, Leduc, Beaumont, Fort Saskatchewan or elsewhere in the region, we can do all of it without an office visit: video meetings, phone calls, e-signing and secure document upload. See how an online mortgage works and the communities I serve.
John Antle, Mortgage Associate | Team Lead, Pineapple National Inc.
General information only, not personalized financial or mortgage advice. Please speak with a licensed mortgage professional about your situation. Approval not guaranteed. O.A.C.
Sources: Canadian Mortgage Trends, “Private lenders warn brokers to look beyond mortgage rates” (September 2026) (opens in a new tab); Pineapple, “The Benefits of Using Alternative Mortgage Lenders” (opens in a new tab).